For a lot of companies, price protection sounds like a smart idea right up until the moment it costs them a fortune.
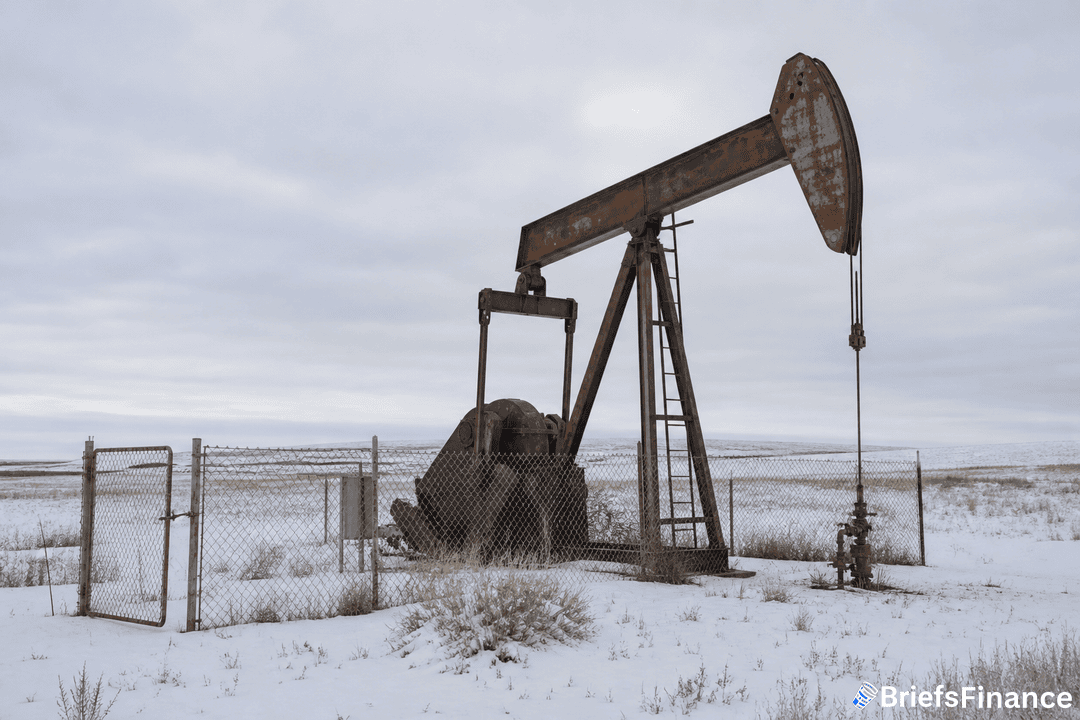
That is exactly what happened to Canadian oil producers this year, and now many of them are walking away from the hedges that were supposed to keep them safe.
Think of a hedge like an insurance policy on the price of oil. A producer agrees to sell a barrel at a set price no matter what, which protects them if prices crash. The trade-off is that when prices soar, they miss out on the extra profit.
This year, that trade-off hurt. When the U.S.-Iran conflict erupted, crude prices jumped fast and hard. Some forecasters are again predicting triple-digit prices as Strait of Hormuz disruptions persist.
For companies that had locked in lower prices, the math got ugly. Baytex has recorded roughly C$113 million in losses from its hedging positions so far this year, versus C$12 million during the same stretch last year. Saturn Oil & Gas Inc. saw about C$150 million in derivative-related losses during the first six months, according to its July 30 earnings call, equal to nearly a quarter of revenue for that period.
Baytex no longer holds West Texas Intermediate hedges as of last quarter and does not expect to add any.
Tamarack Valley Energy Ltd. plans to lower hedged output to roughly 20% from about 50%. International Petroleum Corp., which operates in Alberta and Saskatchewan, has carried no WTI or Brent price protection since the start of July.
Earlier in the year, oversupply warnings and the possible return of Venezuelan barrels led companies to buy put options locking in prices around $60 a barrel. When the war drove prices higher, those hedges lost value and limited gains. Now producers are exiting, hoping the good times last.
Tamarack is changing its strategy to use wider collars, with call and put strikes farther apart, so it keeps more upside from oil price spikes. Obsidian Energy Ltd. is the outlier here, increasing hedging for the third quarter of 2026, citing war-driven price gains and its need to pay down debt.
The 2026 U.S. futures strip has risen roughly 40% since January, which means the market is pricing in continued strength, but that can reverse quickly.
"Everyone lost their appetite for hedging as soon as prices spiked, even though technically you should have countercyclical interest," said Rory Johnston, founder of Commodity Context Corp. "When you're losing money, you should probably be putting on hedges."
Canadian producers are following the longer-running retreat by U.S. shale firms, whose healthier balance sheets made price protection less necessary. A number of firms have also improved their balance sheets through asset sales and deals, including Tamarack Valley's sale of its Charlie Lake properties and Saturn's bond refinancing.
"Financial oil hedging has become less popular after a painful period of realized losses and improving balance sheets," said Ayisha Zia, senior research analyst at Wood Mackenzie. "The Canadian sector is not abandoning risk management, but it is becoming more selective."
The bottom line: When oil prices eventually cool, and they usually do, these producers will have to explain why they gave up the safety net. For investors, the question is whether the cash that would have gone to cover hedges ends up in your pocket or back into the ground.