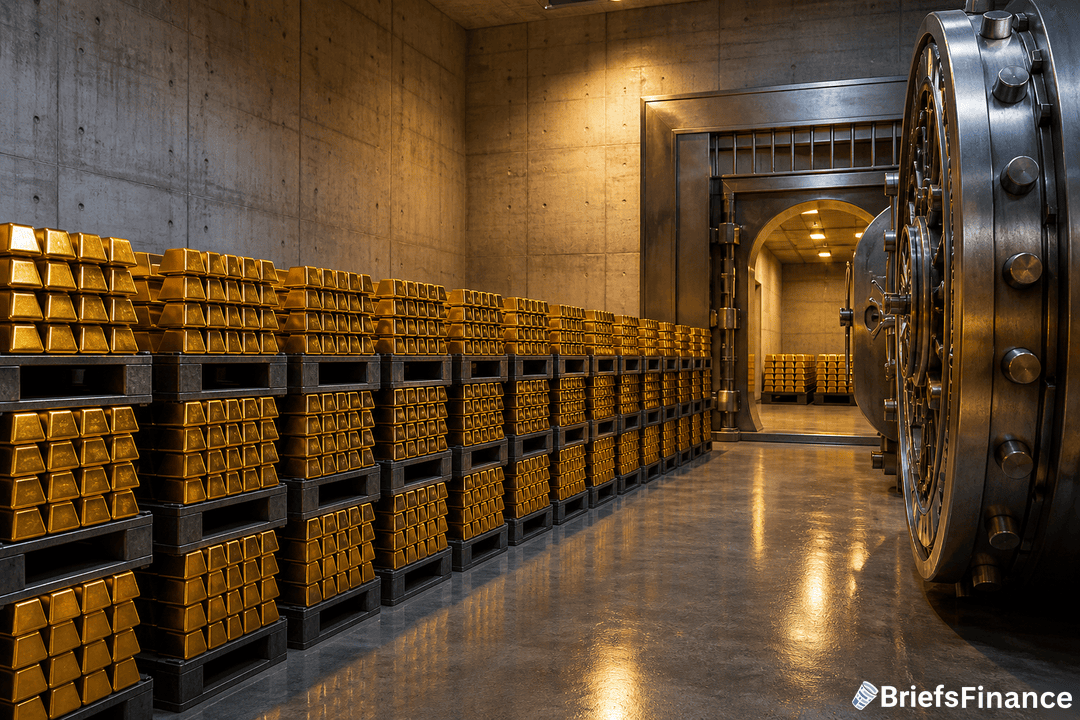
If you want to know how reserve managers actually feel about the dollar, watch what they do with their gold.
For three years in a row, they have bought more than 1,000 tonnes of it, which is the cleanest signal in this entire de-dollarization conversation.
The World Gold Council confirmed central banks added 1,045 tonnes of gold to reserves in 2024, following 1,051 tonnes in 2023 and a record 1,136 tonnes in 2022 - three straight years above 1,000.
The 2010 to 2021 annual average was 473 tonnes, which means today's pace is more than double that of the prior decade.
Q4 2024 alone saw 333 tonnes of central bank gold purchases, with buyers spread across emerging markets:
The Czech National Bank, the National Bank of Hungary, and the State Oil Fund of Azerbaijan also stepped up their buying.
The European Central Bank's June 2025 study on official-sector gold demand pulled the geopolitics into focus, with central bank gold demand accounting for more than 20% of global gold demand in 2024.
In the 2010s, that average was about 10%, and gold became the second-largest global reserve asset by market value in 2024 behind only the dollar.
In a World Gold Council survey of about 60 central banks, the top three reasons for holding gold were a long-term store of value, performance during crises, and portfolio diversification. One in four central banks in emerging and developing economies cited "concerns about sanctions" or "anticipation of changes in the international monetary system" as a reason to hold more gold.
The ECB also flagged a structural shift, since before 2022 gold prices moved opposite to US real yields as a classic inflation hedge, while after Russia's invasion of Ukraine that relationship broke and geopolitical risk became the bigger driver.
In 5 of the 10 largest annual increases in central bank gold share since 1999, the country involved faced sanctions in the same year or the year before.
Reserve managers are not retail traders, and they do not trade for momentum.
When the National Bank of Poland sets a target of 20% gold allocation, that decision sticks for years, and when Turkiye, India, and China collectively add more than 600 tonnes since the end of 2021, that is not a tactical move.
The dollar share of global reserves has drifted from 72% in 2001 to about 56% today, while the gold share has gone the other way, with reserve managers voting on what they trust over a 30-year horizon.
The IMF's reported gold reserve numbers only capture about 34% of estimated central bank demand, so the actual buying may be even bigger than the headlines.