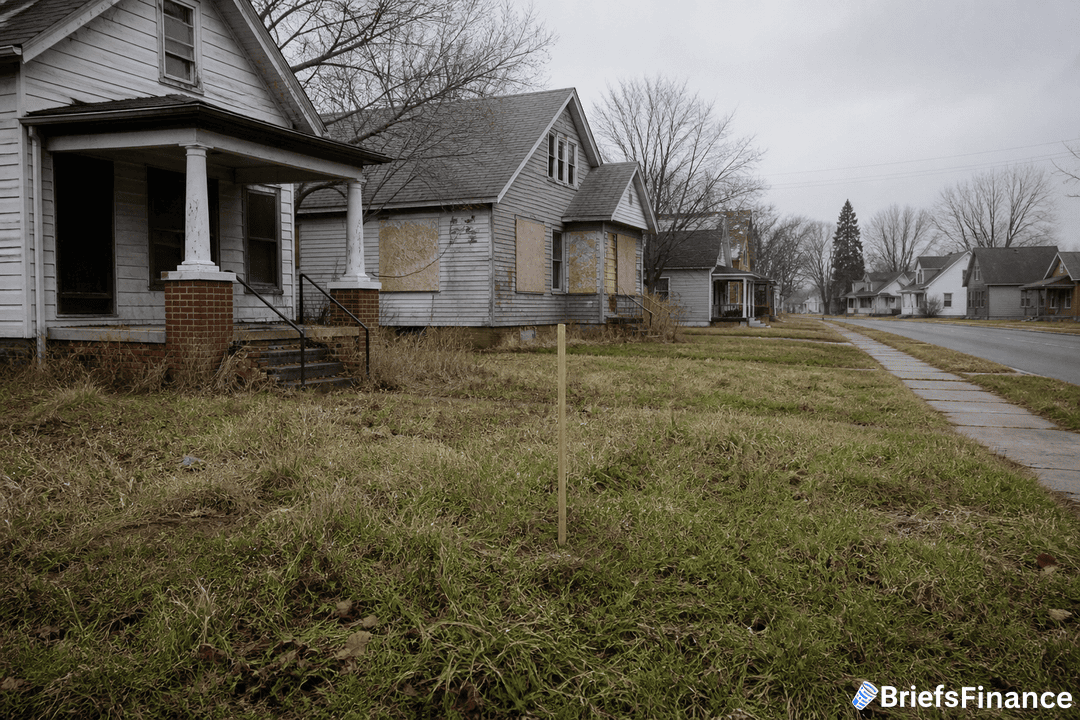
Ask a young person what they want from the housing market these days, and the answer might surprise you. They want it to fall apart.
On the surface, it makes sense. Prices have stretched so far beyond what a typical salary can support that a downturn looks like the only door left open.
The last major U.S. housing crash, which ran from 2007 through 2009, did something remarkable. It cut home values sharply, pushed foreclosures up, and created a stretch where homes were genuinely cheap for buyers who came after the dust settled. That memory lingers. For a generation that has watched prices climb for their entire adult lives, the idea of a repeat feels less like a disaster and more like a shot at the American dream.
But experts say the wish comes from a real place, even if the logic has holes. Morissa Schwartz, who studies housing trends, put it this way: "Gen-Z is not rooting for a recession. They are rooting for a reset. When wages, mortgage rates, down payments, inventory, and prices all feel fixed against them, the price becomes the one visible number they imagine can move."
Here is what the crash fantasy tends to leave out. The 2008 downturn did not just lower prices. It wrecked the job market, tightened credit until almost nobody could borrow, hurt family wealth, and slowed the pace at which young people could form their own households.
The numbers tell that story. Federal Reserve data shows homeownership among young adults fell from 45% in 2005 to 36% in 2014. That is not a blip.
That is an entire decade where ownership moved further away, even as prices became more affordable. A Federal Reserve Bank of Minneapolis report found that today only 22% of adults under 35 own a home.
Dell Jeanty, another housing expert, points out that the math does not work even in a crash scenario. "Because of high living costs, even a major drop in home prices would still leave homeownership out of reach for many Gen-Z without more substantial salary growth or other financial help," she said.
The survey backs that up. These are not people who are one price cut away from buying a house. They are people trying to get stable enough to pay rent.
Here is the uncomfortable truth hiding in the data. A cheaper listing alone will not make ownership possible. Schwartz said it directly: "A cheaper listing still may not be affordable if income growth, mortgage rates, down-payment savings, insurance, taxes, and lending standards remain unfavorable."
That means even if prices fell by a third, the monthly payment on a home could still be out of reach if mortgage rates stay high and wages stay flat. Meanwhile, the costs around homeownership keep climbing. "Housing has become one of the most visible and difficult costs for households to manage, as inflation continues to raise rents, homeownership expenses, and other essential living costs," Jeanty said.
So what would a real reset look like? Not a crash that brings the economy down with it, but a slow repricing that meets buyers where they actually are. That means wages that keep pace with costs.
It means down-payment help or lending standards that do not punish first-time buyers. It means a market where the price tag is not the only number standing between a renter and a mortgage.
For anyone under 35 watching this from their parents' spare bedroom, the takeaway is not to root for disaster. A crash might make headlines, but it will not make the math work. The path to ownership runs through income growth and savings, not through watching the market burn.
That is a slower, less dramatic story. But it is the one that actually ends with keys in your hand.